Subscribe
Logo
Logo
  • Topics Icon Topics
    • AI Icon AI
    • Banking Icon Banking
    • Blockchain/DeFi Icon Blockchain/DeFi
    • Embedded Finance Icon Embedded Finance
    • Fraud/Identity Icon Fraud/Identity
    • Investing Icon Investing
    • Lending Icon Lending
    • Payments Icon Payments
    • Regulation Icon Regulation
    • Startups Icon Startups
  • Podcasts Icon Podcasts
  • Products Icon Products
    • Webinars Icon Webinars
    • White Papers Icon White Papers
  • TechWire Icon TechWire
  • Search
  • Subscribe
Reading
Two Significant Reports Just Published on P2P Lending
ShareTweet
Home
Peer to Peer Lending
Two Significant Reports Just Published on P2P Lending

Two Significant Reports Just Published on P2P Lending

Peter Renton·
Peer to Peer Lending
·Aug. 15, 2014·3 min read

Yesterday, two major reports were published on the p2p lending industry. First, the Federal Reserve Bank of Cleveland put out a positive report on the future potential growth of this industry and the same day Fitch Ratings published a more sobering report on where the p2p lending industry stands today. Both make for some very interesting reading.

Federal Reserve Bank of Cleveland logo

First let’s take a look at the report from the Cleveland Fed. This is a quick read containing some very interesting graphs. It is focused on interest rates, particularly their comparison with average credit cards rates. I found the chart below interesting.
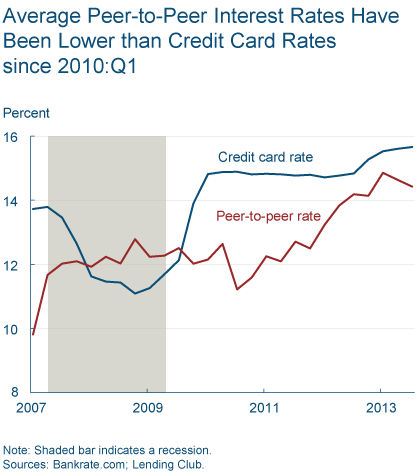
Credit card vs p2p lending interest rates

So, on average credit card interest rates have been significantly higher than the average rates at Lending Club. It appears that the Cleveland Fed did not use data from Prosper in their analysis. What is even more interesting is the fact that peer to peer loans have been performing slightly better than credit cards when it comes to the percentage that are delinquent.

On average, between 2010:Q2 and 2014:Q1, 3.2 percent of peer-to-peer loans were past due compared to 3.7 percent of standard consumer finance loans. Over this period, peer-to-peer loans had a lower share of poorly performing loans in 10 of 16 quarters.

The conclusion of the report is that p2p lending will continue to grow because borrowers find it an attractive alternative to credit cards and there is strong investor demand.

There are three major credit ratings agencies in the US: Standard & Poors, Moodys, and Fitch Ratings. These businesses are very important to the financial system because institutional investors use these ratings to make investment decisions. They rate the credit worthiness of debt issued by corporations and governments as well as asset backed securities.

Last month Standard & Poors rated a securitization by SoFi and that was very big news for this industry. Yesterday, Fitch Ratings released a report on peer to peer lending – this follows on from the Standard & Poors coverage from a couple of months ago. That major ratings agencies are starting to take notice.

I was able to obtain a copy of the Fitch report and it makes for some interesting reading – unfortunately the full report is not available publicly. It is helpful for those of us, like myself, who are sanguine about the industry’s future to stop and see how some impartial financial analysts view p2p lending. While the message comes through that Fitch believes the industry does indeed have great potential they do not have enough confidence yet that it will realize this potential.

Here is a summary of their concerns:

  • Platforms have limited operating history – no company has been around long enough to have weathered multiple economic cycles.
  • Rising interest rates could have an adverse impact – both investor and borrower demand could reduce in a rising interest rate environment.
  • Regulatory risk remains elevated –  they take the view regulations could change – in fact they believe that p2p lenders should be mandated to retain a portion of their loan book.

For these reasons Fitch states that any rating for this debt will be below investment grade and even then they would only consider a debt rating from one of the major platforms. This makes the “A” rating that SoFi received from S&P last month all the more impressive.

Many investors have the same concerns that Fitch has. These are all valid concerns that I hear regularly and they are part of the reason why many people still view this industry with skepticism. The way I look at it is this. As investors we are being compensated very well for risking our investment in this asset class. For me, the three concerns above are not enough to dissuade me from investing. But it is a good reminder that this asset class is still relatively new and it is not without risk.
  • Peter Renton
    Peter Renton

    Peter Renton cofounded Fintech Nexus as the world’s largest digital media company focused on fintech before it was acquired by Command. Peter has been writing about fintech since 2010 and he is the author and creator of the Fintech One-on-One Podcast, the first and longest-running fintech interview series.

    View all posts

Tags
credit riskFederal ReserveFitch Ratings
Related

Peter Renton looks at how AI is Changing Banking 

Stablecoins on the Menu as Fed Meets in Jackson

Alloy provides compliance regulations roadmap for financial institutions, fintech partners

Sponsored Sponsored content is a type of promotional media paid for by an advertiser but created and shared by a publisher. Fintech Nexus contracts sponsored content articles to experienced journalists comfortable in the fintech space.
The Federal Reserve building

How Not to Enter Banking

Popular Posts

Today:

  • FundedFunded: Zenskar lands $15M to rebuild billing for AI-era finance teams Apr. 17, 2026
  • Pranav MistryAI Wearables Are Entering Boardrooms, But Are The Safety Rules Ready? Dec. 3, 2025
  • FNDouble raises $6.5M from investors including Jack Altman and YC to make accountants twice as powerful Dec. 11, 2025
  • Basis CofoundersFUNDED: Basis Lands $100M as AI Agents Move From Copilots to Full Workflows in Accounting  Feb. 27, 2026
  • FN1No Backspace in the Physical World – Building AI for 5,000-lb Machines Apr. 9, 2026
  • What is Really Going on With Private CreditWhat is Really Going on With Private Credit Apr. 30, 2026
  • Kasra KhademOPINION: Finance Found Its AI Moment. Mortgage Slept Through It. Jun. 18, 2026
  • Funded – 6/26/26Funded: Attention raises $30M as AI sales software shifts from note-taking to action Jun. 26, 2026
  • Ryan WigginsMercury’s Ryan Wiggins on Building Customer Trust: Lessons from a Decade at Facebook and WhatsApp Jul. 2, 2026
  • TitoEscaping the demo: The founders building the foundation for medtech physical AI Jul. 23, 2026

This month:

  • FUTURE NEXUS IMAGE TEMPLATES!! (2)OCC Hints at Trouble for Charters Jun. 18, 2026
  • Nikhil ChandokFrom YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone Oct. 22, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • FNMerge CEO on building the pipes behind AI, and starting with zero code May. 21, 2026
  • Sam TegelElectronX CEO Sam Tegel on Building a New Market from Scratch Aug. 13, 2026
  • Hannah BozianAmerican Express’s Hannah Bozian on What 176 Years of Payments Teach Us About AI Agents Oct. 15, 2026
  • nikhil_bharadwaj_ceo_xeal_energyThe Next AI Data Center Could Be in Your Parking Garage Oct. 29, 2026
  • FNDouble raises $6.5M from investors including Jack Altman and YC to make accountants twice as powerful Dec. 11, 2025
  • FN1Pigment co-CEO Eléonore Crespo wants to give CFOs superpowers Mar. 19, 2026
  • Nic BairdThe $10,000 inference trap: A former pro sailor’s fix for AI’s money problem Oct. 1, 2026

More News
  • About
  • Contact
  • Disclaimer
  • Privacy Policy
  • Terms
Subscribe
Copyright © 2026 Fintech Nexus
  • Topics
    • AI
    • Banking
    • Blockchain/DeFi
    • Embedded Finance
    • Fraud/Identity
    • Investing
    • Lending
    • Payments
    • Regulation
    • Startups
  • Podcasts
  • Products
    • Webinars
    • White Papers
  • TechWire
  • Contact Us
Start typing to see results or hit ESC to close
lis digital banking USA Lending Club UK
See all results