Subscribe
Logo
Logo
  • Topics Icon Topics
    • AI Icon AI
    • Banking Icon Banking
    • Blockchain/DeFi Icon Blockchain/DeFi
    • Embedded Finance Icon Embedded Finance
    • Fraud/Identity Icon Fraud/Identity
    • Investing Icon Investing
    • Lending Icon Lending
    • Payments Icon Payments
    • Regulation Icon Regulation
    • Startups Icon Startups
  • Podcasts Icon Podcasts
  • Products Icon Products
    • Webinars Icon Webinars
    • White Papers Icon White Papers
  • TechWire Icon TechWire
  • Search
  • Subscribe
Reading
How a credit card interest rate cap could affect Brazil’s fintech industry
ShareTweet
Finance Minister of Brazil, Fernando Haddad
Home
Fintech
How a credit card interest rate cap could affect Brazil’s fintech industry

How a credit card interest rate cap could affect Brazil’s fintech industry

Jorge C. Carrasco·
LatAm
·May. 10, 2023·2 min read

Few government measures have recently worried Brazil’s fintech industry more than the possible capping of interest rates on prepaid cards.

A few weeks ago, amid an intense campaign to push through several reforms in the Brazilian economy, Brazil’s Minister of Finance Fernando Haddad criticized the “stratospheric” revolving credit card interest rates and said he would seek to limit how much banks and fintechs can charge customers in this regard.

Revolving credit card interest fees are charged when the customer misses a bill or pays only part of the total amount. In Brazil — a country where defaults have increased substantially in the last few months — this modality is one of the most used by consumers.

The revolving credit rate reached 411.5% per year in January 2023, representing the highest level since August 2017.
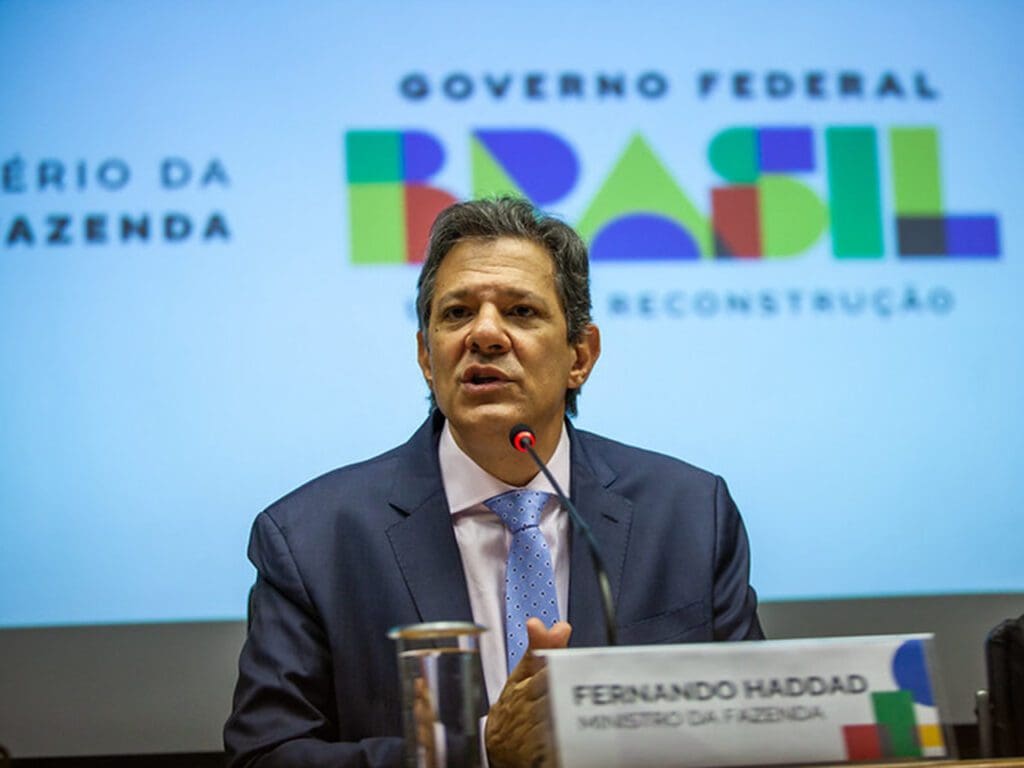
Fernando Haddad is the Minister of Finance of Brazil.
Fernando Haddad, Brazil’s Minister of Finance.

Fintechs could be affected the most

Despite strong resistance from the financial sector, which fears losing an essential part of its resources, the Ministry of Finance will implement measures to reduce the rates in the coming weeks.

The final design is still uncertain. But a recent report by Goldman Sachs pointed to see a higher downside risk to the return on equity (ROE) of fintechs like Nubank and Banco Inter.

“Still, from this perspective, we see higher downside risk to the earnings of Inter (38%-56%) and Nu (16%-24%), while incumbents would have negative variance between 2% and 9%,” the report pointed out.

These assumptions by the U.S. bank are based on analyses of a mix of revolving loans disclosed by the companies themselves and on the industry average for companies that do not disclose this information. In addition, the 60-day default rates of 50% of the revolving portfolio, the other half of which does not accrue interest, were also considered.

For Goldman Sachs analysts, implementing a cap on revolving credit card rates may be quite challenging. Given the widespread use of interest-free installment plans by the Brazilian population, such a charge cap may negatively impact banks, retailers, and consumers.

The social side of the issue

On the other hand, Haddad said two weeks ago, in a meeting with bankers to discuss the issue, that “the current structure (of revolving credit cards) is hurting the low-income population a lot. According to the minister, a good part of the delinquent population can’t escape the spiral of high fees charged for late payments on credit cards.

Interest-free transactions represent the majority of the total transactions in the Brazilian banking and fintech system, at 73%. This makes it so that the entire credit risk is priced into revolving and financing installments to be viable for card issuers.

Related:

Brazilian fintech Creditas cuts losses in Q1 and looks for first profits

Last week, Nubank CEO David Vélez said that the eventual setting of a cap on credit card interest rates could be ‘very damaging’ to the financial system and could potentially strip away the ability to offer credit to millions of people.

“If this were to happen arbitrarily, tens of millions would lose their cards the next day because the operation would no longer be profitable. It would be a shock to the system”, said the executive in an interview with Valor Econômico.

  • Jorge C. Carrasco
    Jorge C. Carrasco

    Jorge C. Carrasco is a Contributing Reporter at Fintech Nexus. He reports on fintech, economy, banking, startups, and technology, covering the most impactful stories from a Latin American perspective.

    He has contributed to several international publications, such as Foreign Policy, The Spectator Australia, Estadão, Época, Washington Examiner, and Quillette. Originally from Havana, Cuba, he is now based in Brazil.

    View all posts
Tags
Brazilcredit cardsfintechLatAmMinister of Financeregulation
Related

The Leaders Driving Fintech Forward

Photo of Raj Date ex CFPB

“Traditional financial institutions do not thrive amidst chaos.”

Ready to Sign Up for a Gen AI Certification Program? Fintech Founders & Others Weigh In on the Trend

LoanPro/Visa DPS integration provides unique credit personalization opportunities

Popular Posts

Today:

  • Andrew DaiThe Missing Piece to AGI Nov. 19, 2026
  • Alec LitowitzThe Real AI Risk Isn’t Superintelligence. It’s Sameness. Aug. 6, 2026
  • Luca TerragniOPINION: Agentic AI’s Big Risk Is Data With No Boundaries Nov. 5, 2026
  • Nikhil ChandokFrom YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone Oct. 22, 2026
  • Tyler NidayA former Deere engineer’s bet on physical AI that works in orchard dust Oct. 8, 2026
  • Victoria ZuoQED Partner Victoria Zuo on Finance’s Human-Not-Present Economy Oct. 8, 2026
  • Dr. Jean NehmeHardware as a durable moat & the former surgeon’s bet on “soft robotic cells” Aug. 27, 2026
  • The Cost of FailureOPINION: Enterprise Cyber Defense is Missing the Proof Layer Aug. 20, 2026
  • Sam TegelElectronX CEO Sam Tegel on Building a New Market from Scratch Aug. 13, 2026
  • Jennifer Lassiter, Standard CharteredScribe CEO Jennifer Smith on what happens when AI joins your team Feb. 26, 2026

This month:

  • Andrew DaiThe Missing Piece to AGI Nov. 19, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • Sam TegelElectronX CEO Sam Tegel on Building a New Market from Scratch Aug. 13, 2026
  • Nikhil ChandokFrom YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone Oct. 22, 2026
  • FUTURE NEXUS IMAGE TEMPLATES!! (2)OCC Hints at Trouble for Charters Jun. 18, 2026
  • Hannah BozianAmerican Express’s Hannah Bozian on What 176 Years of Payments Teach Us About AI Agents Oct. 15, 2026
  • FNMerge CEO on building the pipes behind AI, and starting with zero code May. 21, 2026
  • FNDouble raises $6.5M from investors including Jack Altman and YC to make accountants twice as powerful Dec. 11, 2025
  • Luca TerragniOPINION: Agentic AI’s Big Risk Is Data With No Boundaries Nov. 5, 2026
  • Fintech 3.0Fintech 3.0 Runs on Stablecoins: Norwest VP Jordan Leites Shares Fintech’s Next Infrastructure Gains Jan. 15, 2026

More News
  • About
  • Contact
  • Disclaimer
  • Privacy Policy
  • Terms
Subscribe
Copyright © 2026 Fintech Nexus
  • Topics
    • AI
    • Banking
    • Blockchain/DeFi
    • Embedded Finance
    • Fraud/Identity
    • Investing
    • Lending
    • Payments
    • Regulation
    • Startups
  • Podcasts
  • Products
    • Webinars
    • White Papers
  • TechWire
  • Contact Us
Start typing to see results or hit ESC to close
lis digital banking USA Lending Club UK
See all results