Subscribe
Logo
Logo
  • Topics Icon Topics
    • AI Icon AI
    • Banking Icon Banking
    • Blockchain/DeFi Icon Blockchain/DeFi
    • Embedded Finance Icon Embedded Finance
    • Fraud/Identity Icon Fraud/Identity
    • Investing Icon Investing
    • Lending Icon Lending
    • Payments Icon Payments
    • Regulation Icon Regulation
    • Startups Icon Startups
  • Podcasts Icon Podcasts
  • Products Icon Products
    • Webinars Icon Webinars
    • White Papers Icon White Papers
  • TechWire Icon TechWire
  • Search
  • Subscribe
Reading
LendingClub outlines cautious approach to support long-term growth
ShareTweet
lending club q42022 presentation
Home
Finance
LendingClub outlines cautious approach to support long-term growth

LendingClub outlines cautious approach to support long-term growth

Isabelle Castro Margaroli·
Finance
·Feb. 8, 2023·2 min read

Following a year that eventually led to a cut of 14% of their workforce, it was perhaps unsurprising that LendingClub referenced the challenging conditions in their Q4 2022 earnings call. 

The company continued to see net revenue growth despite the ongoing macroeconomic difficulties. 

“We closed out 2022 With solid results,” said Scott Sanborn, CEO of LendingClub, in the opening remarks. “Both revenue and earnings were near the high end of our guidance range. And importantly, we took action to position the company well to navigate current headwinds.”
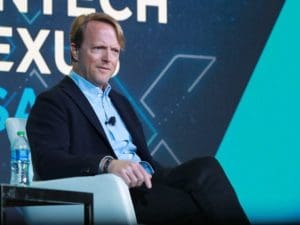
LendingCLubs Scott Sanborn at the Fintech Nexus USA Conference on May 26, 2022
LendingClub’s Scott Sanborn at Fintech Nexus USA Conference on May 26, 2022.

“For the full year, we generated 45% revenue growth and a record 290 million net income.”

Deposits had also grown by 104% YOY, and the company had scaled the online banking platform acquired in early 2021. 

However, loan originations were down. Drew LaBenne, CFO of LendingClub, commented that total revenue had remained flat due to an offset created by the 29% decline in non-interesting revenue due to this drop in originations.

Marketplace revenue was also hit and saw a reduction of $47.2 million between 2021 and 2022. The company stated the drop was due to the pace of Federal Reserve interest rate increases and tighter underwriting standards implemented by the company.

Looking Forward

Sanborn took a favorable position looking forward, stating that the company will focus on what they “can control” amid an uncertain economy. 

The focus will be split into three areas. 

  1. “Continuing to manage credit quality through the cycle prudently.” – Sanborn stated that he felt focusing on quality rather than quantity was vital for the company to navigate forward. He explained that the rate environment had continued to put pressure on the marketplace volumes and, as a result, restricted the relative value the company has provided. He noted that the company’s delinquencies had performed above market average due to their cautious underwriting approach. 
  2. “Preserving profitability and maintaining a strong balance sheet.” – Sanborn mentioned the recent “streamlining of operations” and cut expenses. In addition, he explained that the acquisition of an additional extensive portfolio of “high-quality seasoned loans” had bolstered the company’s net interest income.  
  3. “Being practical and focused in our products and technology investments.” – Sanborn explained that the company was slowing down on investment going into 2023 due to the macroeconomic conditions. However, he assured that the company would focus on “putting the building blocks in place” for future investment opportunities in the year ahead. 

In light of the ongoing macroeconomic storm, the guidance for Q1 2023 was cautious but positioned to maintain a trajectory along the three focus points. 

The provision for credit losses going into the new year has been set at $62 million, $21 million lower than Q4 2022. LaBenne stated that this was “primarily due to a decrease in the dollar amount of loan originations held on the balance sheet.”

Pre-provision revenue was set between $55-$70 million, lower than the amount seen in Q4 for both 2022 and 2021, despite a growth of 12% between the two years. 

Guidance for total originations was set between $1.9-$2.2 billion, with the company maintaining its underwriting strategy and focus towards “quality over quantity.”

RELATED: Fintech Ticker Table

  • Isabelle Castro Margaroli
    Isabelle Castro Margaroli

    Isabelle is a journalist for Fintech Nexus News and leads the Fintech Coffee Break podcast.

    Isabelle's interest in fintech comes from a yearning to understand society's rapid digitalization and its potential, a topic she has often addressed during her academic pursuits and journalistic career.

    View all posts
Tags
Earningsearnings reportLending Clublendingclub
Related

Affirm hits it out of the park with their earnings

MoneyLion reports on record-breaking quarter in Q1

LatAm’s Mercado Libre plows ahead with 50M fintech clients

LendingClub exceeds expectations in strong Q1 earnings

Popular Posts

Today:

  • Basis CofoundersFUNDED: Basis Lands $100M as AI Agents Move From Copilots to Full Workflows in Accounting  Feb. 27, 2026
  • FN1No Backspace in the Physical World – Building AI for 5,000-lb Machines Apr. 9, 2026
  • FundedFunded: Zenskar lands $15M to rebuild billing for AI-era finance teams Apr. 17, 2026
  • What is Really Going on With Private CreditWhat is Really Going on With Private Credit Apr. 30, 2026
  • Kasra KhademOPINION: Finance Found Its AI Moment. Mortgage Slept Through It. Jun. 18, 2026
  • Funded – 6/26/26Funded: Attention raises $30M as AI sales software shifts from note-taking to action Jun. 26, 2026
  • Ryan WigginsMercury’s Ryan Wiggins on Building Customer Trust: Lessons from a Decade at Facebook and WhatsApp Jul. 2, 2026
  • TitoEscaping the demo: The founders building the foundation for medtech physical AI Jul. 23, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • Hannah BozianAmerican Express’s Hannah Bozian on What 176 Years of Payments Teach Us About AI Agents Oct. 15, 2026

This month:

  • FUTURE NEXUS IMAGE TEMPLATES!! (2)OCC Hints at Trouble for Charters Jun. 18, 2026
  • Nikhil ChandokFrom YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone Oct. 22, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • FNMerge CEO on building the pipes behind AI, and starting with zero code May. 21, 2026
  • Hannah BozianAmerican Express’s Hannah Bozian on What 176 Years of Payments Teach Us About AI Agents Oct. 15, 2026
  • Sam TegelElectronX CEO Sam Tegel on Building a New Market from Scratch Aug. 13, 2026
  • FN1Pigment co-CEO Eléonore Crespo wants to give CFOs superpowers Mar. 19, 2026
  • nikhil_bharadwaj_ceo_xeal_energyThe Next AI Data Center Could Be in Your Parking Garage Oct. 29, 2026
  • Rodney RobinsonTabaPay CEO on the Moat AI Can’t Replace Jun. 25, 2026
  • Nic BairdThe $10,000 inference trap: A former pro sailor’s fix for AI’s money problem Oct. 1, 2026

More News
  • About
  • Contact
  • Disclaimer
  • Privacy Policy
  • Terms
Subscribe
Copyright © 2026 Fintech Nexus
  • Topics
    • AI
    • Banking
    • Blockchain/DeFi
    • Embedded Finance
    • Fraud/Identity
    • Investing
    • Lending
    • Payments
    • Regulation
    • Startups
  • Podcasts
  • Products
    • Webinars
    • White Papers
  • TechWire
  • Contact Us
Start typing to see results or hit ESC to close
lis digital banking USA Lending Club UK
See all results