Subscribe
Logo
Logo
  • Topics Icon Topics
    • AI Icon AI
    • Banking Icon Banking
    • Blockchain/DeFi Icon Blockchain/DeFi
    • Embedded Finance Icon Embedded Finance
    • Fraud/Identity Icon Fraud/Identity
    • Investing Icon Investing
    • Lending Icon Lending
    • Payments Icon Payments
    • Regulation Icon Regulation
    • Startups Icon Startups
  • Podcasts Icon Podcasts
  • Products Icon Products
    • Webinars Icon Webinars
    • White Papers Icon White Papers
  • TechWire Icon TechWire
  • Search
  • Subscribe
Reading
Merchants battle against the costs of cashless
ShareTweet
payments
Home
Fintech
Merchants battle against the costs of cashless

Merchants battle against the costs of cashless

Isabelle Castro Margaroli·
Fintech
·Jan. 18, 2023·3 min read

The march towards a cashless future is well underway. 

The British Retail Consortium (BRC) found in its 2022 payments survey that card transactions within the UK accounted for almost 90% of retail transactions in 2021. 

The BRC noted that cash usage had dropped significantly to an all-time low of 15% yet remained the second most used payment method after debit cards.

While the ongoing pandemic measures may explain the cash drop, a wave of cashless options for payments and budgeting has materialized. Budgeting apps and mobile banking have become the tools of choice for the younger, more tech-savvy generations. Cash is essential for specific demographics; however, the organization predicted that users would continue to drop, reaching 6% of all retail purchases in 2031.
Graph showing growth
Source: The BRC Payments Survey 2022

Card processing fees soar in the cashless environment. 

While card payments may be more convenient, they carry costs critical to the retailer’s financial health. 

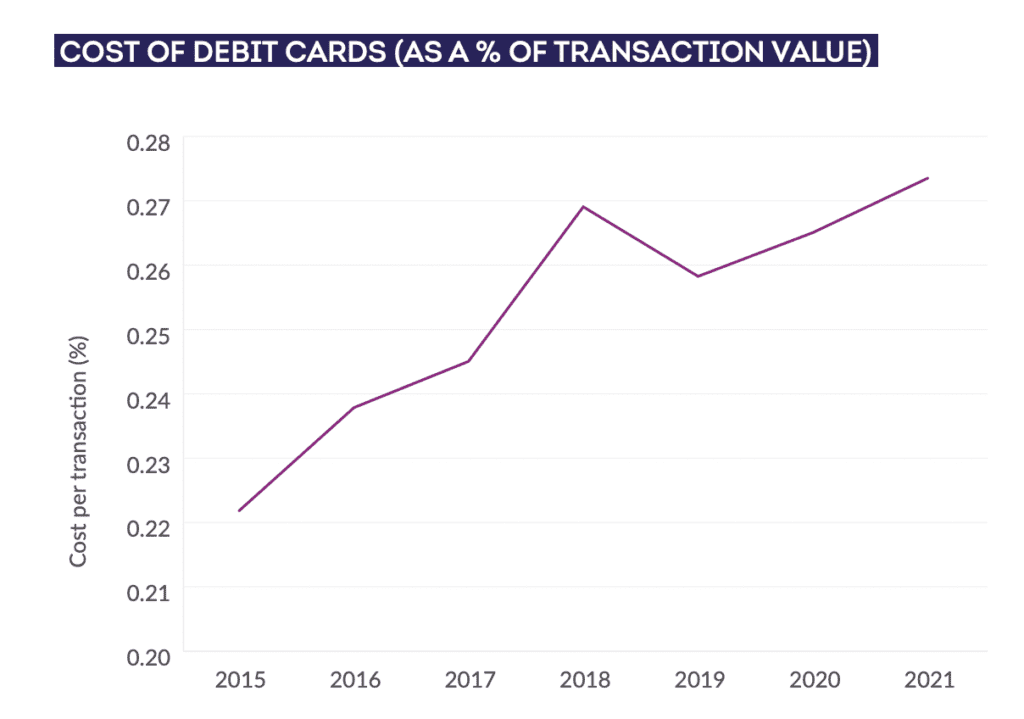
The BRC found that in 2021, retailers spent £1.15 billion on processing card transactions, with the average fees for using a debit card rising significantly. This, paired with the higher volume of transactions, resulting in an additional £141 million spent on debit card transactions. 

As part of the “Axe the Card Tax” Campaign, led by the BRC and other organizations, it was noted these rising fees are part of a trend. The initiative claims that card payment “scheme and processing” fees have recently increased by around 600%, stating that the current system is “anti-competitive.” The hardest hit is SMEs, which are more susceptible to cost fluctuations within a challenging economic environment. 

To combat this, the BRC and other companies are turning to increased adoption of open banking as a source of hope. 
Brian Hanrahan, CEO of Nuapay

Brian Hanrahan, CEO of Nuapay, said, “While card payments are a familiar and relatively safe option for retailers, merchants should consider leveraging open banking for customer payment processes.” 

“For merchants, open banking is an easy and efficient method for facilitating consumer transactions compared to cash or cards and is more cost-effective. Open banking enables account-to-account (A2A) payments, which have significantly lower per-transaction costs than card payments.” 

How open banking could help 

Adopting alternative payment options driven by open banking frameworks comes with challenges. The BRC has noted that consumers continue to rely on card services, citing a lack of incentive to switch. 

“Without any incentive to switch, consumers still rely on retailers offering card services as a payment option and are very likely to continue…until offered a material reason to change,” the report stated. 

This could result in an impasse where retailers are reluctant to introduce new payment options without consumers’ demand, despite the associated savings. Conversely, their customers are likely only to switch if the option is useful and widely accepted.

Increases in open banking solutions have, however, left their mark. In a study published by Nuapay, 25% of merchants believed that it could become the most popular payment method within the next 5 years, citing an increase in uptake over the past two years.

Online checkouts have seen the most adoption, including additional options for A2A payment without significant disruption. An increase in mobile wallets and contactless transactions could assist in-person usage.

“The survey results are encouraging, demonstrating a step change in merchant awareness and appreciation of open banking payments. The increase in uptake observed by respondents and predictions for the technology to become the most popular payment method in the next 5 years point to a growing understanding of the value of open banking,” said Hanrahan.

This could spell the end of the “uncompetitive” payment processing environment for merchants while providing options to meet consumers’ diverse needs.  

  • Isabelle Castro Margaroli
    Isabelle Castro Margaroli

    Isabelle is a journalist for Fintech Nexus News and leads the Fintech Coffee Break podcast.

    Isabelle's interest in fintech comes from a yearning to understand society's rapid digitalization and its potential, a topic she has often addressed during her academic pursuits and journalistic career.

    View all posts
Tags
A2A paymentscashlessnuabankOpen Bankingpayments
Related

Renton’s Take on Loan Model Risks

BREAKING: Money20/20: The Download

Green Dot’s GM of Embedded Finance on Banking Transparency

Fintechs Take On AI x Fraud

Popular Posts

Today:

  • 2026 FintechWhat does 2026 hold for Fintech?  Jan. 29, 2026
  • Fraud used to be a craftThe ID Document Is Dead. The Industry Just Hasn’t Buried It Yet. Jul. 9, 2026
  • FN1Through the Crypto Telescope Nov. 20, 2025
  • Alloy President Laura SpiekermanAlloy President Laura Spiekerman on Agentic AI and Identity Risk Apr. 2, 2026
  • HumanX_recapHumanX: Between Prophecy and Procurement Apr. 9, 2026
  • Stephanie Sher, Founder, Integral VenturesIntegral Ventures’ Stephanie Sher is all about seeing diamonds in the rough May. 14, 2026
  • FNMerge CEO on building the pipes behind AI, and starting with zero code May. 21, 2026
  • Fonoa (2)Funded: Fonoa raises $110M to build the operating system for autonomous tax May. 29, 2026
  • FUTURE NEXUS IMAGE TEMPLATES!! (2)OCC Hints at Trouble for Charters Jun. 18, 2026
  • Ryan WigginsMercury’s Ryan Wiggins on Building Customer Trust: Lessons from a Decade at Facebook and WhatsApp Jul. 2, 2026

This month:

  • FUTURE NEXUS IMAGE TEMPLATES!! (2)OCC Hints at Trouble for Charters Jun. 18, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • Nikhil ChandokFrom YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone Oct. 22, 2026
  • FNMerge CEO on building the pipes behind AI, and starting with zero code May. 21, 2026
  • Sam TegelElectronX CEO Sam Tegel on Building a New Market from Scratch Aug. 13, 2026
  • Hannah BozianAmerican Express’s Hannah Bozian on What 176 Years of Payments Teach Us About AI Agents Oct. 15, 2026
  • Rodney RobinsonTabaPay CEO on the Moat AI Can’t Replace Jun. 25, 2026
  • FN1Pigment co-CEO Eléonore Crespo wants to give CFOs superpowers Mar. 19, 2026
  • Nic BairdThe $10,000 inference trap: A former pro sailor’s fix for AI’s money problem Oct. 1, 2026
  • Anders RanumSapphire Ventures Partner Anders Randum on Relationship Building with Founders Sep. 17, 2026

More News
  • About
  • Contact
  • Disclaimer
  • Privacy Policy
  • Terms
Subscribe
Copyright © 2026 Fintech Nexus
  • Topics
    • AI
    • Banking
    • Blockchain/DeFi
    • Embedded Finance
    • Fraud/Identity
    • Investing
    • Lending
    • Payments
    • Regulation
    • Startups
  • Podcasts
  • Products
    • Webinars
    • White Papers
  • TechWire
  • Contact Us
Start typing to see results or hit ESC to close
lis digital banking USA Lending Club UK
See all results