Mexican digital payments system Cobro Digital, or CoDi, has been around for more than two years in the country.
Yet a large part of the population is unaware of it, and just a few rely on it for everyday payments, data from the regulator shows.
CoDi was an ambitious initiative put forward by the regulator in 2019 to facilitate financial transactions and promote inclusion.
But, it has gotten off to a slow start with some 7 million registered users in a country with a population of 130 million.
What is more, just 840,088 accounts have reported at least one transaction, according to data provided by Banco de Mexico.
Further south in Latin America, another regional powerhouse has moved along a similar path. Yet to the contrary, its adoption rates have been stunning, raising questions on the causes of such widespread success.
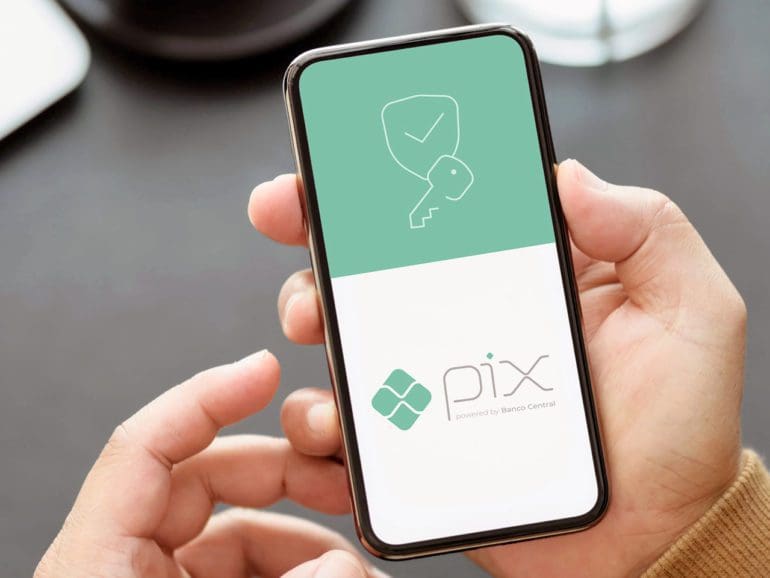
Banco Central do Brasil launched Pix in 2020, and in less than a year, it gained massive adoption among the population.
It reached monthly transactions worth $140 billion instead of roughly $0.16 billion accumulated in CoDi payments ever since its inception.
Numbers are overwhelming
By almost every measure, the numbers look overwhelming tilted towards Pix. More than 500 transactions are processed through Pix every second. That adds up to roughly 30,000 a minute and over 40 million per day.
“Pix is a success story,” said Paulo Oliveira Andreoli, head of Omnifinance at Grupo FCamara Consulting. “It was quickly adopted by Brazilians as it is a very practical payment method, easy to use, safe and free of charge.”
Both CoDi and Pix are fast retail payment systems that allow users to execute real-time payments. They are low-cost and have the distinction of being available 24 hours a day, every day of the year, through a network operated by central banks in each country.
But there are also differences in how the system is designed, the level of embracing by financial participants, and intrinsic preferences between two different societies.
First things considered, there is the cash factor. While cash is king in Mexico and the unbanked represent a large portion of the population, the use of electronic money was already widely spread in Brazil before the arrival of Pix. It is a country with a high rate of credit and debit card penetration and a greater level of banked adults.
Structure makes a difference
The structure design also makes a difference.
According to the Bank of International Settlements, one crucial distinction of Pix is its openness. The BiS argues that while only certain registered financial institutions are allowed to operate CoDi, in the case of Pix, three different types of players are permitted, including payments firms as well as fintechs.
In practice, some 774 firms have signed up to offer Pix in Brazil, including banks, credit unions, payments fintechs, and state-run institutions. In the case of CoDi, regulator data shows that, as of now, just three banks — BBVA, Banamex, and Bancoppel — account for as much as 90% of all CoDi reported accounts.
For some, the embracement from financial players in Brazil was a critical success driver.
“The Brazilian banking sector, in general, is one of the most innovative and technological in the world,” Henrique Marise, a payments manager at Brazilian bank Pan, said. “It is already bringing to the table numerous initiatives on how to operate the PIX sustainably, taking advantage of the opportunities it offers.”
For him, the predominant factor was the involvement of the Central Bank governing the entire operation. In his view, its role was essential to promote Pix and guarantee a level-playing field for participants.
“The experience will be very similar regardless of your bank or payment institution,” he said.
“Pix has had unparalleled adoption in Brazil, and that will facilitate digitization going forward,” said Enrique Ramos O’Reilly, director at Mexican firm Temenos.
“In Mexico, Codi has not had as much support and diffusion leading to a much more limited success.”
As of March 2022, more than 113.7 million individuals and some 8.5 million companies have registered to use Pix.
Peer to peer continues to be the significant source of transactions, contributing to 72% of all dealings. Almost two-thirds of Pix users are below 40 years old.