Subscribe
Logo
Logo
  • Topics Icon Topics
    • AI Icon AI
    • Banking Icon Banking
    • Blockchain/DeFi Icon Blockchain/DeFi
    • Embedded Finance Icon Embedded Finance
    • Fraud/Identity Icon Fraud/Identity
    • Investing Icon Investing
    • Lending Icon Lending
    • Payments Icon Payments
    • Regulation Icon Regulation
    • Startups Icon Startups
  • Podcasts Icon Podcasts
  • Products Icon Products
    • Webinars Icon Webinars
    • White Papers Icon White Papers
  • TechWire Icon TechWire
  • Search
  • Subscribe
Reading
Data consent and Infrastructure could stop FI Hyper-personalization
ShareTweet
banking
Home
artificial intelligence
Data consent and Infrastructure could stop FI Hyper-personalization

Data consent and Infrastructure could stop FI Hyper-personalization

Isabelle Castro Margaroli·
Fintech
·Sep. 7, 2023·3 min read

Personalization has become an essential component of how fintechs bring value to customers. 

In a survey conducted by Twilio, 62% of consumers said they expect personalization from brands, and a further 49% stated they would become repeat buyers if it was offered. As the facility becomes even more integral to online experiences, hyper-personalization becomes the next port of call. 

Building on the utilization of data and AI seen in the personalization of online services, hyper-personalization creates a real-time personalized experience for consumers. 

“It’s a word that we’re using, in my opinion, to describe a tactical bridge that will take us to the promise of open finance and the democratization of finance,” said Farouk Ferchichi, President of Envestnet Data & Analytics. 

He explained that, currently, traditional financial institutions are facing three key challenges when adapting to consumer needs. 

  1. Keeping up with the rapidly changing consumer profile as new generations and demographics with different needs access the market. 
  2. Growing competition, particularly from fintechs.
  3. A mismatch between the speed of innovation and the company’s vision for their service. 

As development continues on AI and data processing capabilities, hyper-personalization could pose an opportunity for financial institutions to address these challenges. “Data and analytics, AI, all of this is really the emerging oil that powers the Financial Engines of the future,” said Ferchichi. 

However, he explained, two things could stand in its way: the dialogue around data consent and financial institutions’ ability to adjust their systems to allow for the new technology.

Data Consent: A Critical Piece Of The Puzzle

“We are in very early stages. We’re scratching the surface,” said Ferchichi. “I think the emergence of artificial intelligence and responsible use of artificial intelligence is built upon a consent-based, consumer data sharing.” 
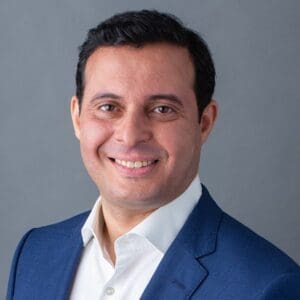
Farouk Ferchichi, President of Envestnet Data & Analytics

The conversation around consumer data sharing is a tumultuous one. As financial services are powered ever more by data, the need to find the balance between sharing data and maintaining privacy has come ever more to light. On the one hand, consumers understand that sharing more data may allow access to better, personalized services but may be deterred by a lack of clarity about who that data will be shared with. 

US regulators, moving toward open banking, are addressing the ambiguity surrounding consumer data. The CFPB announced steps towards updating personal data rights in August, and multiple bills related to consumer data privacy were introduced over the course of 2023. 

Ferchichi said that these moves may have accelerated the pace of acceptance. 

“At the heart and soul of making that transaction of shared value is going to be the consent management process,” he said. “Enabling the consumer to actually consent, how deep, how far and what can their data gets used for.” 

But all that new data means very little if financial institutions’ infrastructure can’t digest it. 

“How financial institutions can actually take advantage of a responsible sharing economy is based on the redesign of customer-facing processes to allow for that consumption of new data.”

FIs need a revamp

“The average person has five different accounts,” he continued. “That connectivity of accounts is having access to the consumer data. It’s giving them the power to consent to give them value in return. To deliver that value, fundamentally, the financial institution has to change their, in some cases, 20-60-year-old processes to be able to consume that data and create new value.”

Built on layers of legacy systems, traditional institutions may face challenges in processing the extra data efficiently. This could affect their ability to implement hyper-personalized products. Ferchichi explained that in order to be effective in hyper-personalization efforts, products would have to be compatible across channels, fitting into the daily lives of consumers. This could make embedded data analytics critical. 

“Having that ability to embed systematically in the design of products, services, as well as experiences for the consumer, using data analytics and make services more intelligent, is the key.”

RELATED:

  • SMB personalization key to community bank, credit union growth
  • The future of the bank branch
  • Isabelle Castro Margaroli
    Isabelle Castro Margaroli

    Isabelle is a journalist for Fintech Nexus News and leads the Fintech Coffee Break podcast.

    Isabelle's interest in fintech comes from a yearning to understand society's rapid digitalization and its potential, a topic she has often addressed during her academic pursuits and journalistic career.

    View all posts

Tags
AIdatahyper personalizationpersonalization
Related

Lawsuit, subpoena, have fintechs revisiting AI

Amdocs study shows increased personalization benefits

Study reveals half of Brits are now more wary of online banking, with online fraud a key concern

Rising digital spending among findings of Alkami, Cornerstone Advisors report

Popular Posts

Today:

  • TitoEscaping the demo: The founders building the foundation for medtech physical AI Jul. 23, 2026
  • Jason RosenNew Credit Scores Are Everywhere: How to Make Sense of This New World Oct. 29, 2026
  • Nic BairdThe $10,000 inference trap: A former pro sailor’s fix for AI’s money problem Oct. 1, 2026
  • Anders RanumSapphire Ventures Partner Anders Randum on Relationship Building with Founders Sep. 17, 2026
  • Dr. Jean NehmeHardware as a durable moat & the former surgeon’s bet on “soft robotic cells” Aug. 27, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • Karan KatyaInside Adyen’s Blueprint for Getting Merchants Ready for Agentic Commerce   Jul. 16, 2026
  • Andrew DaiThe Missing Piece to AGI Nov. 19, 2026
  • The Cost of FailureOPINION: Enterprise Cyber Defense is Missing the Proof Layer Aug. 20, 2026
  • 196The Situational Awareness $45B Fallout – AI’s Big Risk is Not AGI, it’s Artificial Consensus Aug. 6, 2026

This month:

  • Andrew DaiThe Missing Piece to AGI Nov. 19, 2026
  • Physical AI’s Picks & Shovels MomentPhysical AI’s Picks-and-Shovels Moment Jul. 23, 2026
  • Sam TegelElectronX CEO Sam Tegel on Building a New Market from Scratch Aug. 13, 2026
  • Nikhil ChandokFrom YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone Oct. 22, 2026
  • FUTURE NEXUS IMAGE TEMPLATES!! (2)OCC Hints at Trouble for Charters Jun. 18, 2026
  • Nic BairdThe $10,000 inference trap: A former pro sailor’s fix for AI’s money problem Oct. 1, 2026
  • Hannah BozianAmerican Express’s Hannah Bozian on What 176 Years of Payments Teach Us About AI Agents Oct. 15, 2026
  • Luca TerragniOPINION: Agentic AI’s Big Risk Is Data With No Boundaries Nov. 5, 2026
  • FNMerge CEO on building the pipes behind AI, and starting with zero code May. 21, 2026
  • Karan KatyaInside Adyen’s Blueprint for Getting Merchants Ready for Agentic Commerce   Jul. 16, 2026

More News
  • About
  • Contact
  • Disclaimer
  • Privacy Policy
  • Terms
Subscribe
Copyright © 2026 Fintech Nexus
  • Topics
    • AI
    • Banking
    • Blockchain/DeFi
    • Embedded Finance
    • Fraud/Identity
    • Investing
    • Lending
    • Payments
    • Regulation
    • Startups
  • Podcasts
  • Products
    • Webinars
    • White Papers
  • TechWire
  • Contact Us
Start typing to see results or hit ESC to close
lis digital banking USA Lending Club UK
See all results